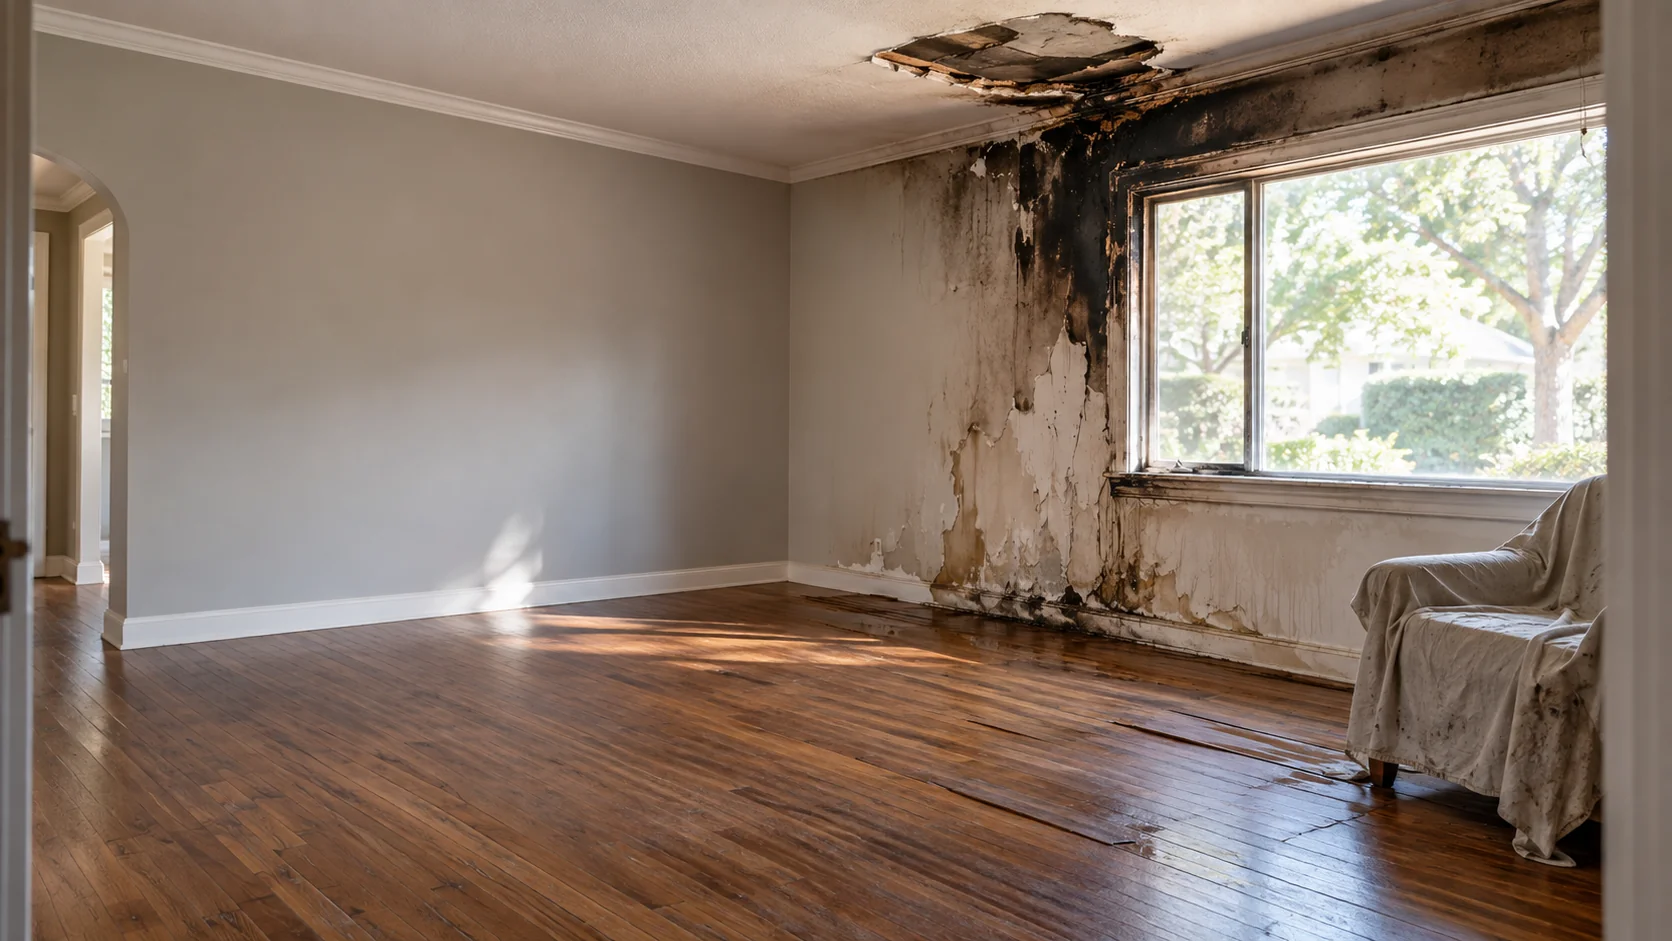
What Makes This Situation Difficult
These are the practical obstacles that make a conventional sale hard here.
Financing is usually unavailable
Lenders will not fund a property with significant unrepaired fire or water damage, so nearly all financed buyers are excluded from the outset.
Remediation is expensive and uncertain
Fire restoration and serious water or mould remediation run into large numbers, and the final figure is often only clear once work is opened up.
Insurance proceeds rarely cover everything
Settlements are frequently less than the true cost to restore, and disputes drag on while the property sits.
Damage spreads
Water damage becomes mould; a fire-damaged structure exposed to weather deteriorates further every month it is left.
Insurability
A damaged property with a claims history can be difficult and costly to insure, which affects any future buyer's ability to close.
Disclosure is unavoidable
Fire and water damage are material and must be disclosed. Selling to a buyer who already understands the condition is a cleaner route than a partial repair you then have to explain.
Your Two Realistic Options
| Sell to Us (Cash) | List With an Agent | |
|---|---|---|
| Remediation before sale | None | Effectively required for a financed buyer |
| Buyer financing | Not applicable — cash | Generally unavailable until repaired |
| Open insurance claim | Workable | Usually needs resolving first |
| Agent commission | No commission charged by us. | Negotiated in the listing agreement |
| Timeline | Close on the date you choose. | Months, after restoration |
| Offer details | We'll make a written offer after we review the property. | Contingent on repairs and lender |
| Gross price | Below restored value | Higher once fully restored |
When You Should Not Sell to Us
If your insurance settlement genuinely covers the cost of proper restoration and you have the time and appetite to manage the work, restoring and then listing will usually net you more. Selling as-is makes sense when the settlement falls short, the claim is contested, or you simply do not want to run a construction project.
Frequently Asked Questions
Will you buy with the insurance claim still open?
Often yes. How the claim and any proceeds are handled needs to be agreed as part of the purchase, and your insurer's terms and your policy govern what is permitted — so tell us early and check with your adjuster.
How much damage is too much?
We have bought properties with major structural fire damage. Extensive damage changes the number rather than our interest, and in the worst cases the value is essentially in the land.
Do I need a remediation or engineer's report?
Not to talk to us. If you already have reports, they help us be more precise. Commissioning them purely for our benefit is not necessary.
Is there mould, and does that matter?
Assume any prolonged water intrusion has produced mould, and tell us if you know it has. It is a standard part of our assessment. It is also a common reason financed sales collapse.
Should I accept my insurer's settlement offer before selling?
That is a decision to make with your own adjuster, broker, or an attorney who handles insurance claims — the settlement affects your position materially and we are not the right party to advise on it.
This page explains how selling a property for cash works. It is not legal, tax or financial advice, and it is not a substitute for advice about your own situation. For anything touching probate, tenancies, foreclosure timelines, divorce settlements, code enforcement or the tax consequences of a sale, please speak to a qualified attorney or CPA. My California Home Solution is a property-buying company, not a brokerage — when we make an offer we are the buyer, not your agent. Richard Farmer is a licensed California real estate broker affiliated with Ktesius Realty Corporation (California DRE License #01842170), so brokerage services are available separately if listing suits you better.